Featured Post


 The Intergovernmental Panel on Climate Change (IPCC) is arguably the most prominent and impactful scientific institution of our time. Their 6th Assessment Reports are the contemporary syntheses of leading scientific research on climate change, risks, mitigation and adaptation and they even contain sections on climate accounting, finance and investment (IPCC, 2022, pp. TS 122-26). But, if you work your way through these reports you struggle to find any research published in accounting and finance journals.
This may be bitterly disappointing to those researchers working at the nexus of accounting, sustainable development and climate change. There is no doubting the scale and scope of the IPCC, but there are many gaps waiting to be filled; gaps which could have been filled by existing accounting and finance research.
For example, they discuss “Innovative financing approaches” and “robust ‘green’ labelling and disclosure schemes”, yet the main focus is on forms of green financing, making no comment on the accounting infrastructures that construct “identifiable low-carbon investment opportunities” (Ibid. p. TS-125, emphasis added). Similar discussions on the need for “Ambitious global climate policy coordination” include arguments on “credible signalling” and “political leadership”, with no mention of the accounting devices underpinning goals-based governance and making that coordination, signalling and leadership possible.
Keeping 1.5°C alive requires a collective response from accounting and finance scholars, aimed at co-ordinating interventions and research that address these critical and pressing gaps in the Sixth Assessment Reports. We cannot allow the IPCC and policy makers to overlook our important research that could make a positive difference or signpost the tried and tested dead ends.
There are many possible reasons for our community being overlooked to date. But if we are to make a positive contribution to the IPCC then we need to change.
The uncomfortable fact is that our work is not being considered in the assessment review process, even when it can provide valuable insights on IPCC priorities. We could go on a ‘woe is me’ tirade, looking to blame others, like economists. Or we could just do something about it; engage.
To do this we need to reflect on questions such as, ‘could my research have contributed to IPCC?’, ‘how can my present and future research contribute to IPCC’ and ‘how could my research help reduce climate change risks?’. We also need to ensure that we, as the CSEAR community, plan and are ready to collectively approach the IPCC with our relevant insights for the next set of assessment reports.
Our special issue of SEAJ provides some contemporary examples of this work. For example:
What we need to bear in mind is that the IPCC only works with peer-reviewed scientific publications and builds on its previous publications. This approach privileges new research findings (since their most recent reports) and research that can be integrated into interdisciplinary scientific research. Their 7th Assessment Reports are unlikely to include research that did not make it into previous six. Therefore, there is a need for new peer reviewed research that references and speaks to the issues already raised in IPCC reports.
So step one is to read and review previous IPCC reports.
This is a mammoth task, too big for one person, but not too big for the CSEAR community if we work together. Given that we only have 5 years until the likely cut off for the 7th Assessment Reports, we argue that it is now time to:
Editor's note: Rob and Ian's commentary is open access (free to download) for all at the SEAJ website at: https://doi.org/10.1080/0969160X.2022.2085131. The contents of the rest of the special issue can be viewed here: https://www.tandfonline.com/toc/reaj20/42/1-2.

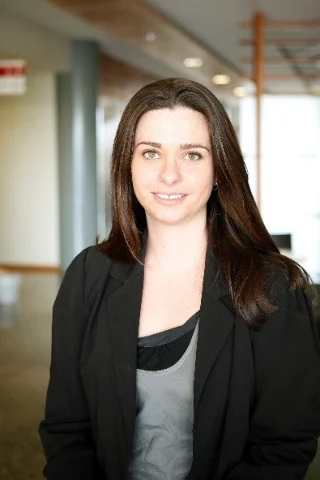
In the first instalment of our Executive Council Spotlight Series, Helen Tregidga reflects on her time with the CSEAR Executive Council, the value of academic community, and the future of social and environmental accounting research.
Hind Hsissou (Audencia Business School) and Keeland McMahon (University of Limerick)
Matthew SOROLA, TBS Business School